A two-bedroom flat in Pereybère
The simplest format to let and to have managed. What you pay, what you could receive under two scenarios, and what can go wrong.
The profile (fictional)
A couple living in Lyon, in their fifties, both Mauritian citizens. They want a property that can be let to travellers and where the family can stay. They have about €80,000 available. Profile made up for the example.
The essentials in three blocks
What you pay
≈ €68,500
out of your pocket at the start, excluding insurance
- Deposit (30% of the price)≈ €33,190
- Purchase tax and notary≈ €6,460
- Zilstone: study, reports, project space≈ €2,090
- Works and furniture≈ €19,000
- Zilstone set-up≈ €4,500
- Bank, survey, licence application≈ €3,260
Then ≈ €700 a month of loan repayments for 15 years, on a loan of ≈ €77,430.
What you receive
What is left each year, after running costs, management and the loan, before tax:
Rent collected: €17,970 to €23,350 a year.
Share of nights let in the year
- 35% : average of all Pereybère listings
- 50% : cautious scenario
- 65% : optimistic scenario
What can go wrong
- If only 35% of nights are let, the Pereybère average: ≈ −€720 a year is left. Any shortfall comes out of your pocket.
- If the loan rate rises to 9%: ≈ €790 a month, and ≈ +€1,470 a year in the cautious scenario.
- If the building’s managing agent refuses holiday letting, no licence is possible. We check their letter before any offer.
Assumptions. Cautious scenario: 50% of nights let, Zilstone’s assumption, above the average of all Pereybère listings (35.3%) [1], because a well-run property compares with active listings, with no certainty. Optimistic scenario: the median of active listings in Mauritius (66%, rounded to 65%) [2]. Average rate: $110 a night [1]. Family stays are not deducted: each blocked week reduces the rent. Before Mauritian tax (15% of rent for a non-resident, to be confirmed [16]) and tax in your country.
Try it yourself
Change the price or the sum you have available: the loan, the repayment and what is left each year update at once.
- Bank loan · 70% of the price
- ≈ €77,430
- Monthly repayment, 15 years at 7%
- ≈ €700
- Out of your pocket at the start
- ≈ €68,500
Amount too small for a loan (banks lend from Rs 1M): a cash purchase, i.e. — out of your pocket.
Your deposit covers everything: purchase with no loan, no monthly repayment.
Deposit too low, cannot be financed as it stands. The bank lends at most 70% of the price, and the costs stay with you. You are short by —.
Visible assumptions: the same rent whatever the price ($110 a night, 50% or 65% of nights let); price between Rs 5.5M and 8.5M, the range of the listings we noted [3]; loan over 15 years, at most 70% of the price and at least Rs 1M (below that, a cash purchase); costs cannot be financed and come out of your deposit: purchase tax, notary, commissions, works (€19,000), set-up, survey and bank fees, worked out as in the details below; your deposit is capped at the cost of a purchase with no loan. This is an exercise, not an offer: no result is guaranteed, and tax is not deducted.
The property and the area
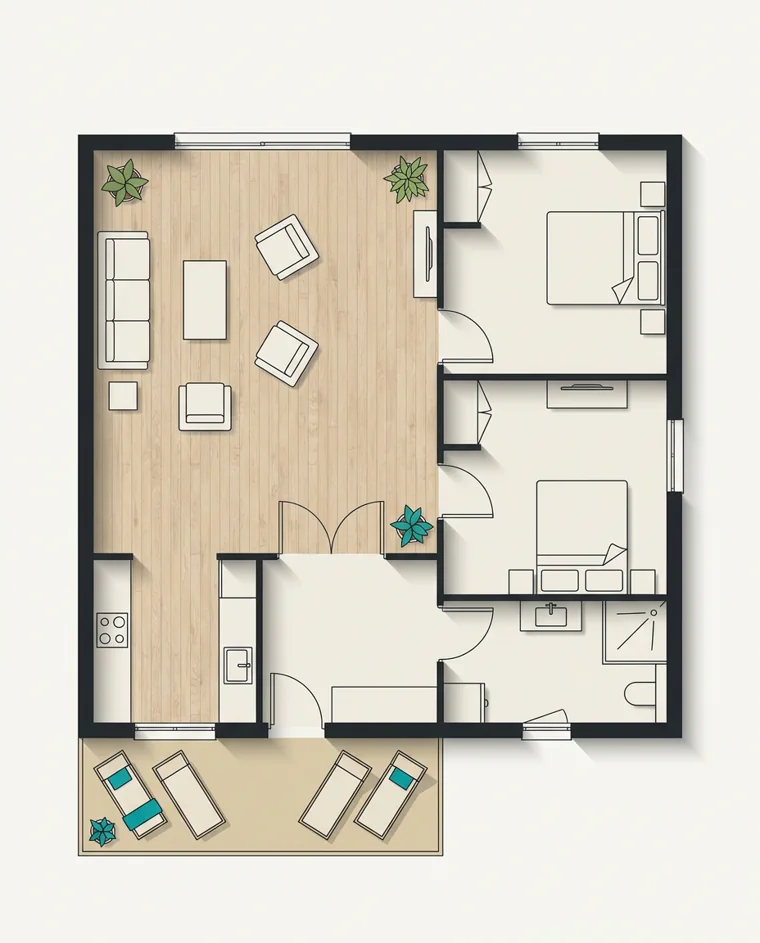
A two-bedroom flat (about 80 m²) in an older residence, a few minutes’ walk from the public beach. Price used: Rs 6M, ≈ €110,620. When we checked on 05/10/2026, we found no comparable two-bedroom listing in Pereybère on the local market; local-market two-bedroom flats were listed at Rs 5.5 to 6.2M in the west (Albion, La Gaulette), and three-bedroom flats in Pereybère at Rs 6.5 to 8.5M [3]. These are asking prices, not sale prices. Schemes open to foreign buyers cost far more: a two-bedroom flat in a RES scheme (Real Estate Scheme, open to foreign buyers) in Grand Baie was listed at Rs 12M [3].
Pereybère has 208 tracked listings, with an average occupancy of 35.3% and an average price of about $110 a night [1]. Guests: couples and families, many French, long stays. Strength: the local beach, next to Grand Baie and its services.
Steps and timing
- Week 120-minute call and one-page pre-study, free.
- Weeks 2 to 4Project study and engagement letter: scoping call, then a written report within 10 business days of receiving the documents.
- Months 1 to 3Search, viewings, checks: surveyor, title, managing agent, permits, price.
- Months 2 to 4Offer, preliminary contract at the notary, loan application.
- Around month 4Completion at the notary, keys handed over.
- Months 4 to 8Works, equipment, letting licence (6 to 10 weeks to process), photos, listings.
- Then, every monthLetting, monthly statement, rent paid into your account.
About 6 to 8 months between the first call and the first guests.
Support fees
| Service | Price and payment | Here |
|---|---|---|
| Scoping call and file opening | invoiced by Zilstone, never refunded on ordering | €200 |
| Your project study | €500 deducted from the set-up price if you take it; if not, it stays due on ordering | €500 |
| Agency commission | at most 2% of the price, invoiced by a REAA-registered estate agency with which we are preparing a partnership, most often paid by the seller on completion, if due from you | €0 |
| Observation reports | €350 per property visited, €900 for 3, due even without a purchase at each visit | €900 |
| Project space | €90 a month or €990 a year, includes the professionals’ calendar monthly or yearly | €990 |
| Set-up | fixed fee of €4,500, no works: compulsory equipment, letting licence, listings go live on set-up | €4,500 |
Launch price list of 06/10/2026. Final Zilstone prices: nothing is added. Agency commission: at most 2%, paid to the agency, most often by the seller; no money moves between Zilstone and the agency. Amounts confirmed in writing in the engagement letter before any commitment. The notary, bank, surveyor and tax adviser bill you directly. Your money never goes through Zilstone. Invoiced in euros or Mauritian rupees. Other currencies are shown for guidance only; any exchange fees are yours.
The detailed figures
The budget, line by line
| Property price | ≈ €110,620Rs 6M |
| Bank loan: 70% of the price, 15 years, 7% | ≈ €77,430 |
| Deposit on the price (30%) | ≈ €33,190 |
| Purchase tax (registration duty, 5%) | ≈ €5,530 |
| Notary (official scale, VAT included) | ≈ €930 |
| Agency commission (at most 2%, most often paid by the seller) | €0 |
| Scoping call and file opening (Zilstone) | €200 |
| Your project study (Zilstone) | €500 |
| Study fee deducted from the set-up price | −€500 |
| Observation reports (3 properties visited) | €900 |
| Project space (1 year, includes the professionals’ calendar) | €990 |
| Works and furniture, coordinated by you with your tradespeople | ≈ €19,000 |
| Zilstone · Set-up (no works: equipment, licence, listings) | €4,500 |
| Bank: arrangement fee (1% of the loan), valuation, mortgage registration (high estimate) | ≈ €2,250 |
| Technical survey before the offer (estimate) | ≈ €920 |
| Letting licence: application fee (Rs 5,000) | €90 |
| Out of your pocket | ≈ €68,500 |
| Insurance (borrower, home) | to be confirmed case by case |
Repayment: ≈ €700 a month. The loan is an assumption: lending on a property to let is usually capped at 70%, and short-term letting must be accepted by the bank, in writing [13]. The MHC Diaspora Home Loan is published from 6.80%, up to 35 years [8].
Both scenarios, line by line
| Cautious | Optimistic | |
|---|---|---|
| Share of nights let | 50% [11] | 65% [2] |
| Average nightly rate | $110 [1] | $110 [1] |
| Rent collected over the year | €17,970 | €23,350 |
| After platforms, running costs, management and licence | €10,950 | €14,300 |
| Loan repayments | −€8,400 | −€8,400 |
| Left per year, before tax | +€2,550 | +€5,900 |
Where your rent goes, out of 100
- Platforms
- Running costs
- Letting management
- For you, before loan and tax
Costs while letting
| Platforms (Airbnb, Booking) | about 12% of income [11] |
| Running costs: energy, building charges, upkeep, insurance | about 14% of income, refined property by property [11] |
| Letting licence (TAC) | application fee Rs 5,000, then Rs 10,000 a year (≈ €180) [12] |
| Cleaning and linen | paid through the guests’ cleaning fees |
| Tourist fee | €3 per night per guest aged 12 or over, paid by the guest and passed on monthly to the MRA; guests with a Mauritian passport are exempt [7] |
| Tax on rent | in Mauritius, 15% for a non-resident under the law, regime to be confirmed with a registered tax agent [16]; in your country of residence, with your tax adviser |
All the risks, in detail
- Occupancy at the Pereybère average (35.3%): ≈ −€720 a year after the loan.
- Loan rate 2 points higher (9%): repayment of ≈ €790; in the cautious scenario, ≈ +€1,470 a year is left.
- The building rules or the managing agent restrict holiday letting: the licence requires a letter from the managing agent and a “tourist residence” use permit in the owner’s name. We check them before any offer.
- Older building: roof waterproofing, damp, wiring. Works may cost more than planned; the survey and quotes come before the offer.
- Competition: active listings in Mauritius grew by 23% in a year [2], faster than tourist arrivals. Nightly rates may fall.
- Heavy rain and cyclones: Pereybère has localised flooding. Insurance and the choice of floor matter.
- Exchange rates: your income is in euros, pounds or dollars; the loan and part of the rent are in rupees. The currency selector at the top uses a fixed rate.
- Resale: no price is guaranteed, and selling costs at most 7% (5% transfer tax and an agency commission of at most 2%).
Rounded figures. Property prices noted in rupees; Zilstone fees in euros; nightly rates published in dollars. Rates fixed on 05/10/2026 (Bank of Mauritius, indicative rates, mid-point between buying and selling), indicative: your bank will apply its own rate.
Sources and assumptions
- AirROI, Airbnb data by market, 12 months to 12/09/2026 (average of all tracked listings) · www.airroi.com
- Airbtics, median of active listings in Mauritius, data of 12/03/2026: 66% occupancy, active listings +23% in a year · airbtics.com
- Local-market listings noted by Zilstone on 05/10/2026 (OFIM, Westimmo, PropertyFinder): asking prices, not sale prices. These properties are not offered by Zilstone. · real-estate-mauritius.mu
- Land (Duties and Taxes) Act: 5% registration duty (buyer), 5% land transfer tax (seller) · www.mra.mu
- Notaries’ scale of fees (Notaries Act 2008), 15% VAT included, to be confirmed by the notary · www.propertymap.mu
- MRA, tourist fee of €3 per night per guest aged 12 or over, since 01/10/2025 · www.mra.mu
- MHC Diaspora Home Loan: from 6.80%, up to 35 years, Rs 1 to 15M; purchase, building, renovation · www.mhc.mu
- Zilstone working assumptions (September-October 2026): platforms ≈ 12% of income, running costs ≈ 14%, loan of 70% of the price over 15 years at 7%, works and furniture ≈ €19,000 for a two-bedroom flat, survey ≈ Rs 50,000; cautious occupancy of 50% for a flat. Launch price list of 06/10/2026
- Tourism Authority: tourist residence licence (TAC), application fee Rs 5,000, then Rs 10,000 a year (type C); use permit and managing agent’s letter required · www.tourismauthority.mu
- Banks: 1% arrangement fee (MCB, minimum Rs 3,000, maximum Rs 50,000, price list of 10/07/2026); valuation Rs 15,000 to 40,000 and mortgage registration capped at ≈ Rs 55,000 (secondary sources, to be checked); lending often limited to 70% for a property to let, to be confirmed by the bank · mcb.mu
- Exchange rates: Bank of Mauritius, consolidated indicative rates of 05/10/2026, mid-point between buying and selling. Indicative: your bank will apply its own rate · www.bom.mu
- Income Tax Act: rent of a non-resident individual taxed at 15% in Mauritius; treatment of holiday letting to be confirmed with a registered tax agent · www.mra.mu
Let’s talk about your project
In 20 minutes, we look at your situation, your budget and what is realistic for you. Free, no commitment.
We are starting our first client journeys.